
Canadian client withholding 15% from your service fees? Plan your Regulation 105 waiver before the next payment
Canadian payers generally must withhold 15% from fees for services performed in Canada unless CRA approves a waiver or reduction. We assess your contract, prepare the application, and help recover tax already withheld.
or call (905) 561-1278
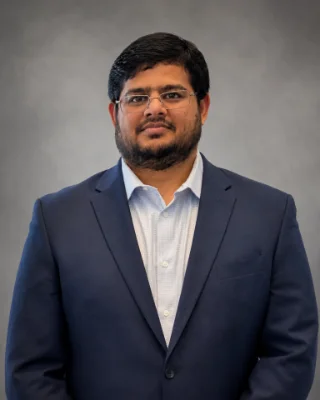
Your file is reviewed by Affan Khalid, CPA, CAOver 20 years of Canadian and international tax experience · 750+ Regulation 105 waiver applications filed · About Affan
- U.S. consultants, contractors and service firms working on site in Canada
- Businesses whose Canadian customer has already withheld 15%
- Canadian companies paying a U.S. service provider
Takes about a minute. We reply by email to confirm whether and how we can help. Submitting does not commit you to an engagement.
Request a Regulation 105 review
Tell us where things stand. We’ll reply by email to confirm whether a waiver or reduction looks supportable.
This site is protected by reCAPTCHA.
How the 15% works
When a non-resident business is paid for services performed in Canada, the Canadian payer generally must withhold 15% of the gross amount and send it to the CRA.
If a contract covers work both inside and outside Canada, a reasonable, documented allocation can limit withholding to the Canadian portion.
The 15% is a prepayment toward any Canadian tax, not the final tax. It still reduces your cash flow. A payer that fails to withhold can be liable for the amount, interest and penalties, so it may require a CRA waiver before paying the full fee.
Submitting a waiver request doesn’t stop withholding. Only an approved waiver or reduction does.
Your customer needs CRA’s authorization letter before it can reduce or stop withholding. Until it has that letter, the usual 15% applies.
The aim is to protect your cash flow from avoidable 15% withholding where CRA grants relief.
Do you qualify for a waiver?
- Your customer withholds 15%Until CRA authorizes a waiver or reduction
- Apply earlyAt least 30 days before work or the first payment
- Choose the routeTreaty-based waiver, or an income-and-expense application
- CRA reviewsIf CRA grants relief, its authorization letter lets your customer reduce or stop withholding
Route 1: Treaty-based waiver
A U.S. business without a permanent establishment in Canada may qualify for a treaty-based waiver. CRA considers the contract, time spent providing services in Canada, treaty terms and other circumstances. Related-party arrangements need careful review, and outstanding Canadian tax liabilities must be resolved before a waiver is issued.
Route 2: Income-and-expense application
If the treaty doesn’t apply, a reduction may still be possible by showing that your actual Canadian tax will be less than 15% of the fee (an income-and-expense waiver).
CRA reviews your estimated Canadian income and expenses, whether the expenses are reasonable, and the tax that results. It may authorize a reduced rate, decline a reduction, or require security, such as a bank guarantee, before waiving withholding. Where the facts support it, Affan can assess and prepare this alternative application.
Work in Québec has a separate 9%
Services performed in Québec are also subject to a separate 9% Québec income-tax withholding, and a CRA waiver does not cover it. Revenu Québec has its own reduction request, and we can prepare both.
When to act
- Before you sign. Confirm where the work will be performed and how the fee splits between Canadian and non-Canadian work.
- At least 30 days before work or the first payment. File the waiver request with the contract and supporting documents. Late requests may still be considered, but approval before payment is less certain.
- If tax has already been withheld, keep the T4A-NR slip. The withheld amount is credited against Canadian tax; any excess may be refunded after a Canadian return is assessed (a T2 for a corporation). A waiver does not remove the Canadian filing requirement.
What to have ready
- Canadian work dates and locations (city and province)
- Who will perform the work: your employees, subcontractors or both
- The Canadian payer’s name and the payment schedule
- Whether the contract includes work performed outside Canada
- Earlier Canadian projects and any existing CRA business number
Please don’t attach contracts to the first message. We’ll arrange a secure upload.
Why Lepore & Company
Cross-border and non-resident tax work for businesses outside Canada.
One coordinated contact
Registrations, withholding relief and filings for your Canadian activity are coordinated in one place, so nothing falls between advisers.
Applications prepared, then followed through
We prepare the waiver application and supporting documents and respond to CRA information requests. Each application is prepared on its own facts, working directly with CRA and, where needed, with your Canadian customer.
CPA oversight
Your file is reviewed by Affan Khalid, CPA, CA, who personally handles communication with CRA waiver officers and follow-up on information requests.
We provide a fixed-fee quote after reviewing your information, generally following the initial call.
Lepore & Company CPA · 145 Highway 8, Stoney Creek, ON L8G 1C1 · (905) 561-1278 · Mon–Fri 8:30 AM – 4:30 PM ET
Why Affan Khalid
Affan Khalid, CPA, CA · Tax Partner & Principal
Over 20 years of Canadian and international tax experience, including senior tax roles at PwC and MNP.
Affan reviews every Regulation 105 file, prepares the application with you, and personally handles communication with CRA waiver officers and follow-up on information requests.
Affan Khalid, CPA, CA has filed more than 750 Regulation 105 waiver applications, with a 100% approval record on those decided by CRA.
Each new application is reviewed on its own facts. Past results don’t guarantee the outcome of a new application.
“This was a big win for me as I launch my new firm, thanks to Affan’s due diligence and ability to urgently get my documents filed.”
Larry P., U.S. business owner
Questions
Does Regulation 105 apply to work we perform entirely in the U.S.?
Generally no. The rule applies to services performed in Canada. Contracts mixing locations need a supported allocation.
Does the Canada–U.S. treaty automatically stop the 15%?
No. The payer keeps withholding until CRA authorizes a waiver or reduction.
Our customer already withheld. Can we get it back?
The withheld amount counts toward any Canadian tax. Any excess may be refunded after a Canadian return is assessed (a T2 for a corporation), using the T4A-NR information.
Does a Regulation 105 waiver also cover our employees’ payroll?
No. Payroll withholding for employees working in Canada is a separate Regulation 102 question, and CPP and EI have their own rules.
How long does CRA take?
CRA asks for requests at least 30 days before the work or first payment and does not guarantee a decision date. We file complete applications early and follow up.
What happens after we send the form?
We review your answers and email you about the next steps, including whether a waiver or reduction may be suitable or what information we still need. We provide a fixed-fee quote after reviewing your information, generally following the initial call. If you engage us, we prepare and file the application and follow up with CRA.
Does Regulation 105 apply to self-employed individuals, or only to companies?
It applies to both non-resident self-employed individuals and corporations. It can also apply to members of partnerships or joint ventures that provide services in Canada. An individual generally claims any excess withholding through a Canadian T1 return rather than a corporate T2 return.
Is the 15% taken from travel costs our customer reimburses?
Not always. CRA has an administrative exception for certain reasonable travel expenses. Some meal and accommodation reimbursements qualify without receipts; higher amounts and transportation expenses generally require the payer to keep supporting receipts. Amounts outside the exception may still be subject to withholding. We can review the invoice and records before your customer pays.
Is the GST/HST on our invoice subject to the 15%?
No. GST/HST charged on services performed in Canada is not subject to Regulation 105 withholding. Whether you must register for and charge GST/HST is a separate question. See our GST/HST and QST registration page.
Do we need a Canadian tax number before applying for a waiver?
Usually. CRA says a corporation without a Canadian business number must register for one. An individual without a Social Insurance Number or individual tax number must apply for an individual tax number using Form T1261. If needed, we can arrange the number application as part of your waiver engagement.
What does CRA look at in an income-and-expense application?
Your expected Canadian fees, the expenses you can reasonably attribute to the Canadian work, and the tax that would result. CRA’s guidance allows set amounts for some travel costs, and higher costs if they are documented. If the estimated tax is lower than the 15% withholding, CRA may authorize a reduced rate.
What happens if CRA doesn’t grant a waiver?
Your customer keeps withholding 15%. The withheld amount still counts toward any Canadian tax, and any excess may be refunded after a Canadian return is assessed. The Canadian filing requirement applies whether or not a waiver is approved.
Related services
These services often come up alongside this one. Start with the review above; we’ll tell you if any of them apply.
Where your situation calls for it, we can also introduce you to Canadian business-banking contacts or an independent Canadian immigration professional. Banks make their own onboarding decisions, and Lepore doesn’t provide immigration advice.
A payment coming up? Check your waiver options first.
or call (905) 561-1278
Related: International tax services · Withholding taxes · Regulation 102 payroll waivers
General information only. Waiver eligibility, the amount subject to withholding, and Canadian return obligations depend on the contract, the activities, the treaty position and CRA review. Submitting an inquiry does not create a professional-client relationship.